Health and Medicare Tips for Seniors
Medicare Advantage Plans: How They Work, Costs, and Extra Benefits
If you have watched television around Open Enrollment, you have seen countless commercials promoting $0-premium Medicare Advantage Plans (Part C). These private insurance plans promise lower monthly costs, prescription drug coverage, and added perks like dental, vision, and gym memberships.
While Medicare Advantage plans can be an excellent fit for many seniors, understanding how they operate—and where the hidden out-of-pocket costs lie—is critical before signing up. Here is everything you need to know about Part C.
How Medicare Advantage (Part C) Actually Works
Medicare Advantage is an all-in-one alternative to Original Medicare. Instead of receiving your healthcare directly through the federal government (Parts A and B), you enroll through a private insurance carrier (such as Humana, UnitedHealthcare, or Aetna).
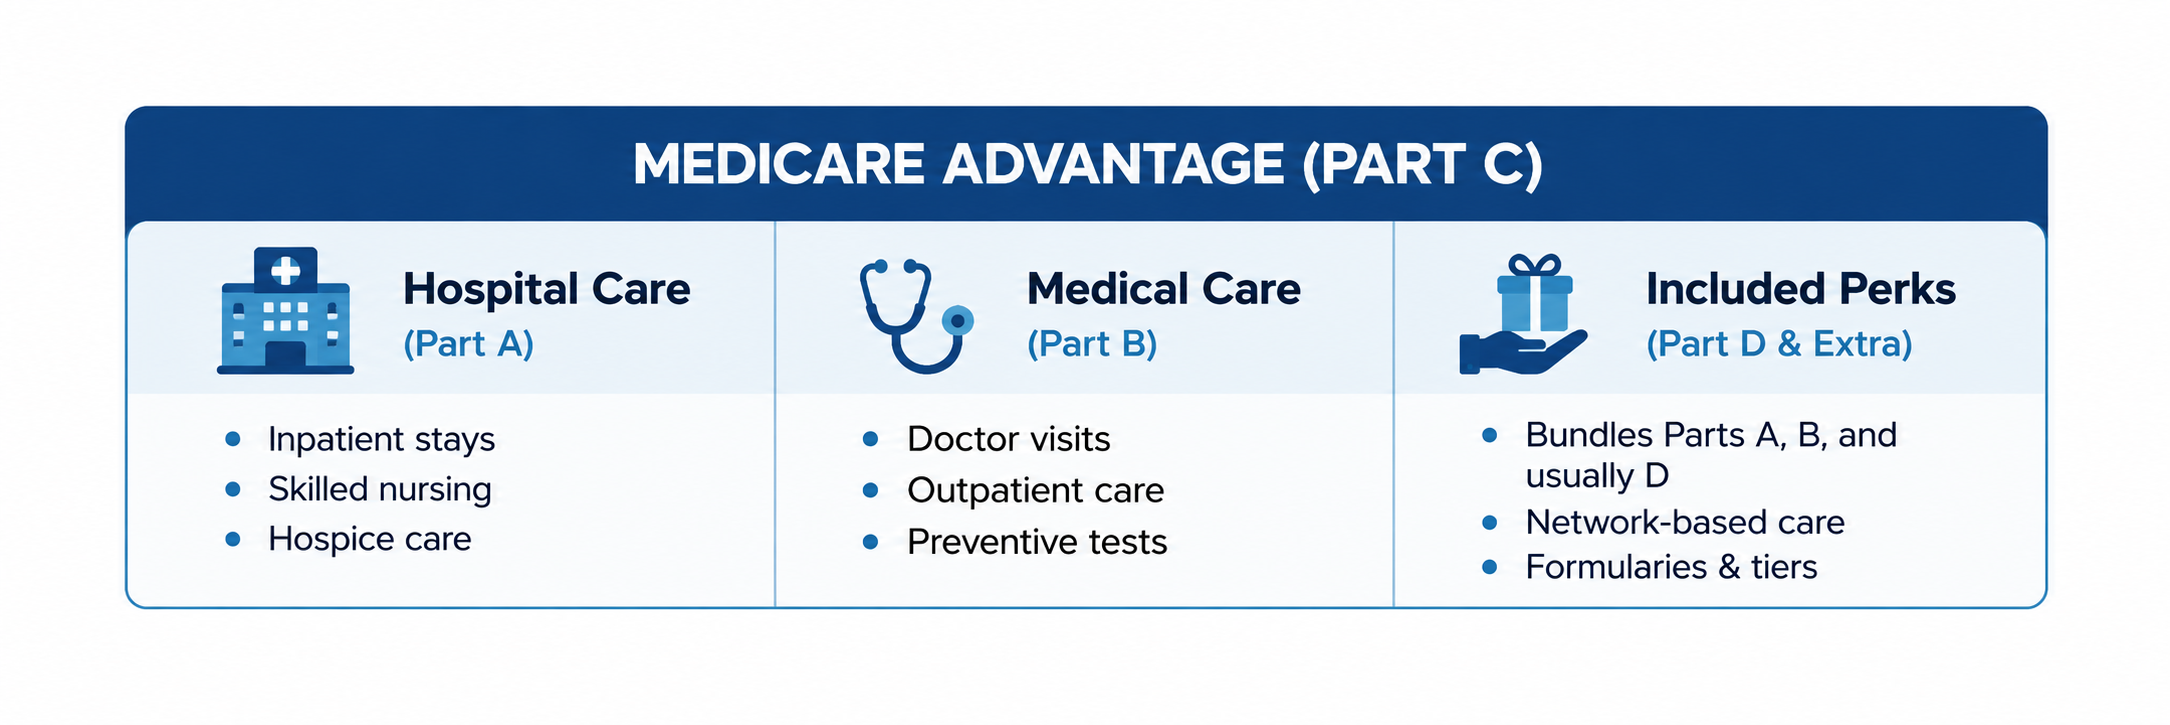
When you join a Medicare Advantage plan:
The Government Pays the Carrier: Medicare pays the private insurer a fixed monthly amount to manage your healthcare.
You Still Pay Part B: You must remain enrolled in Medicare Part A and continue paying your monthly Part B premium.
One Single Member ID Card: You use your private insurance card at doctors and pharmacies instead of your red, white, and blue Original Medicare card.
The Core Advantages of Part C
Why do so many beneficiaries choose Medicare Advantage?
$0 or Low Monthly Plan Premiums: Many plans charge $0 in additional monthly premiums beyond your standard Part B premium.
Bundled Prescription Drug Coverage (MAPD): Most plans include Part D drug coverage, eliminating the need to buy a separate standalone drug policy.
Built-in Maximum Out-of-Pocket Cap (MOOP): Unlike Original Medicare (which has no limit on what you can spend out of pocket), Medicare Advantage plans cap your annual in-network healthcare costs (up to $9,250). Once you reach this cap, the plan pays 100% of covered services for the rest of the year.
Extra Supplemental Benefits: Original Medicare does not cover routine dental, vision, or hearing services. Advantage plans frequently include allowances for:
Dental Care: Cleanings, X-rays, and routine fillings.
Vision & Hearing: Annual eye exams, eyewear allowances, and hearing aid discounts.
Fitness & OTC: Free gym memberships (e.g., SilverSneakers) and quarterly allowances for over-the-counter health items.
The Hidden Fine Print: What to Watch Out For
Despite the low premiums, Medicare Advantage plans require trade-offs that can affect your care during major health events:
1. Doctor Network Restrictions
Most Advantage plans are structured as HMOs or PPOs:
HMO Plans: You must use in-network doctors and specialists; seeing an out-of-network provider usually means paying 100% of the cost yourself.
PPO Plans: You can see out-of-network doctors, but you will pay significantly higher copays or coinsurance.
2. Prior Authorizations & Referrals
Unlike Original Medicare, private Advantage plans often require your primary doctor to obtain prior authorization (approval from the insurance company) before scheduling MRIs, surgeries, specialist visits, or inpatient rehabilitation.
3. Pay-As-You-Go Medical Costs
While monthly premiums are low, you pay copays for almost every service you use—such as $35 for specialist visits, $90+ for emergency room care, or daily copays for inpatient hospital stays.
Is Medicare Advantage Right for You?
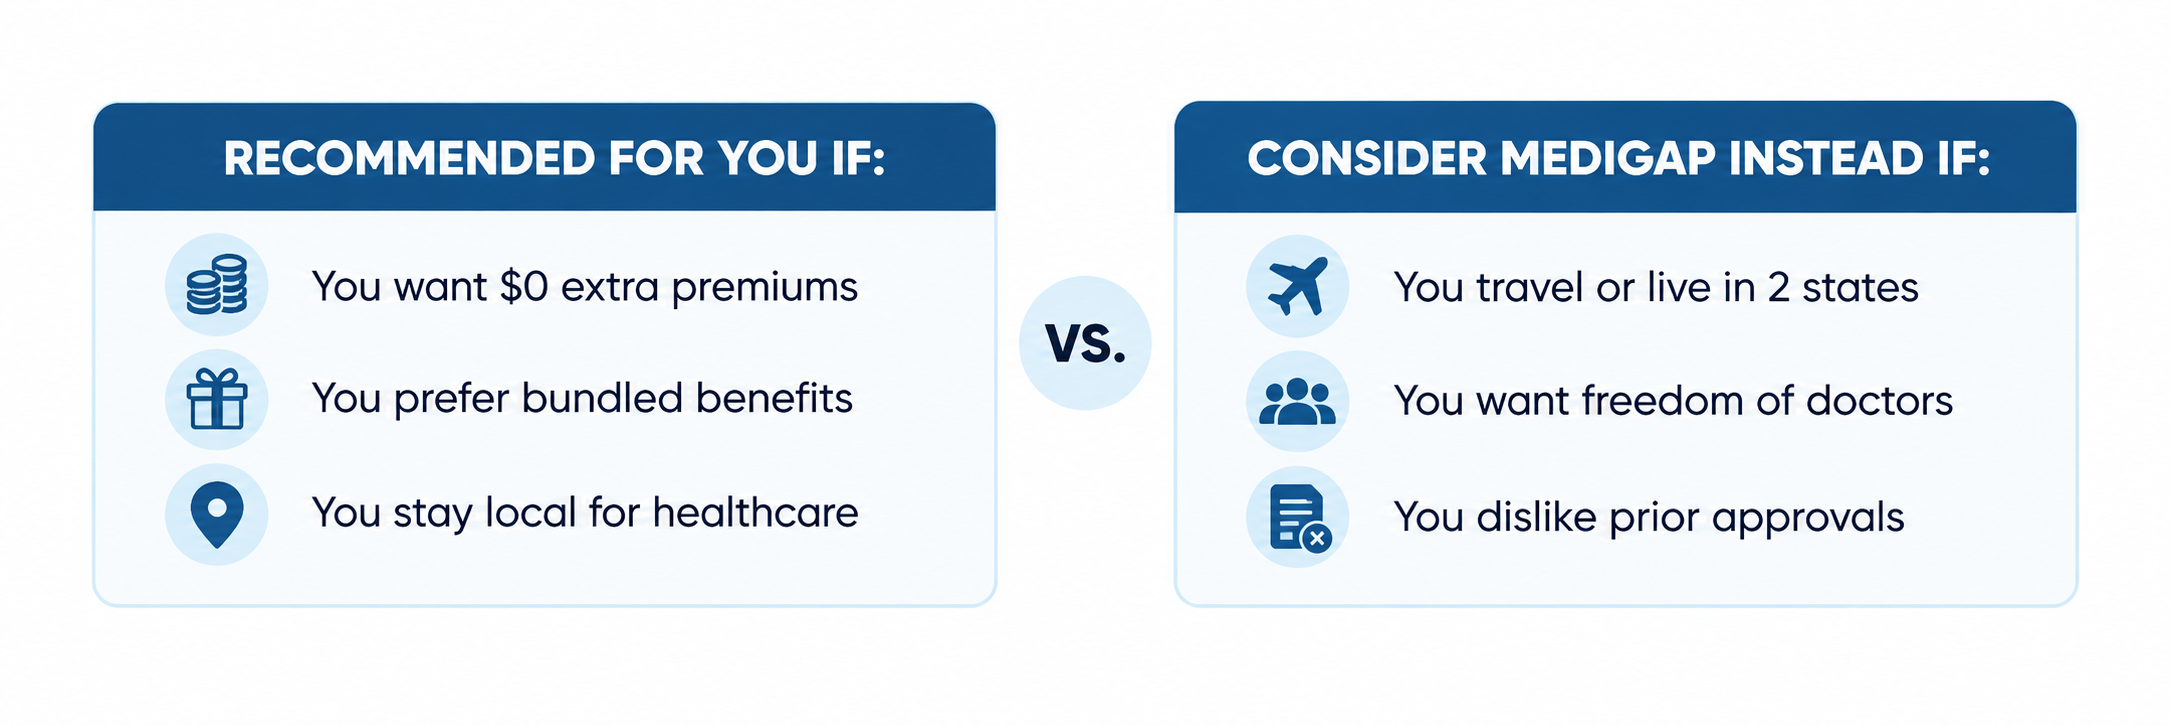
How to Choose the Right Plan in Your Area
Because Medicare Advantage options vary by county, you should evaluate local plans using these 3 criteria:
Check Doctor Availability: Confirm your primary care physicians and preferred hospitals are in the plan’s network.
Verify Your Prescription Drugs: Search the plan's specific medication list (formulary) to ensure your daily drugs are covered at low copays.
Review Benefit Allowances: Check the annual caps on dental, vision, and hearing benefits to ensure they match your personal healthcare needs.
Need help comparing local Medicare Advantage options against Original Medicare and Medigap? Contact our licensed Medicare advisors today for a personalized plan review tailored to your doctors, prescriptions, and budget.
HNeed Help Navigating Your Options?
Connect with an Independent Licensed Insurance Broker who can walk you through your options and help you make a confident decision.
📞Lauren Metzer Call: (412) 770-6477 TTY 711 M-F (9AM - 5PM) to connect with a Licensed Medicare Insurance Agent
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options. Not connected with or endorsed by the United States government or the federal Medicare program.

METZLER HEALTH SOLUTIONS
LEGAL

Disclaimer: Not affiliated with or endorsed by the government of Federal Medicare program. Medicare has neither reviewed nor endorsed this information. For accommodations of persons with special needs, please call 888-576-7550 TTY 711 (M-F 9am-5pm). By calling this number you will be directed to a licensed insurance agent. Not affiliated with or endorsed by the government of Federal Medicare program.
We do not offer every plan available in your area. Currently, we represent 8 organizations which offer 63 products in your area. Please contact Medicare.gov, 1‑800‑MEDICARE, or your local State Health Insurance Program to get information on all of your options.
© Copyright 2026. Metzler Health Solutions. All Rights Reserved.