Health and Medicare Tips for Seniors
Defining the ABC’s of Medicare: Parts A, B, C, and D Explained Simply
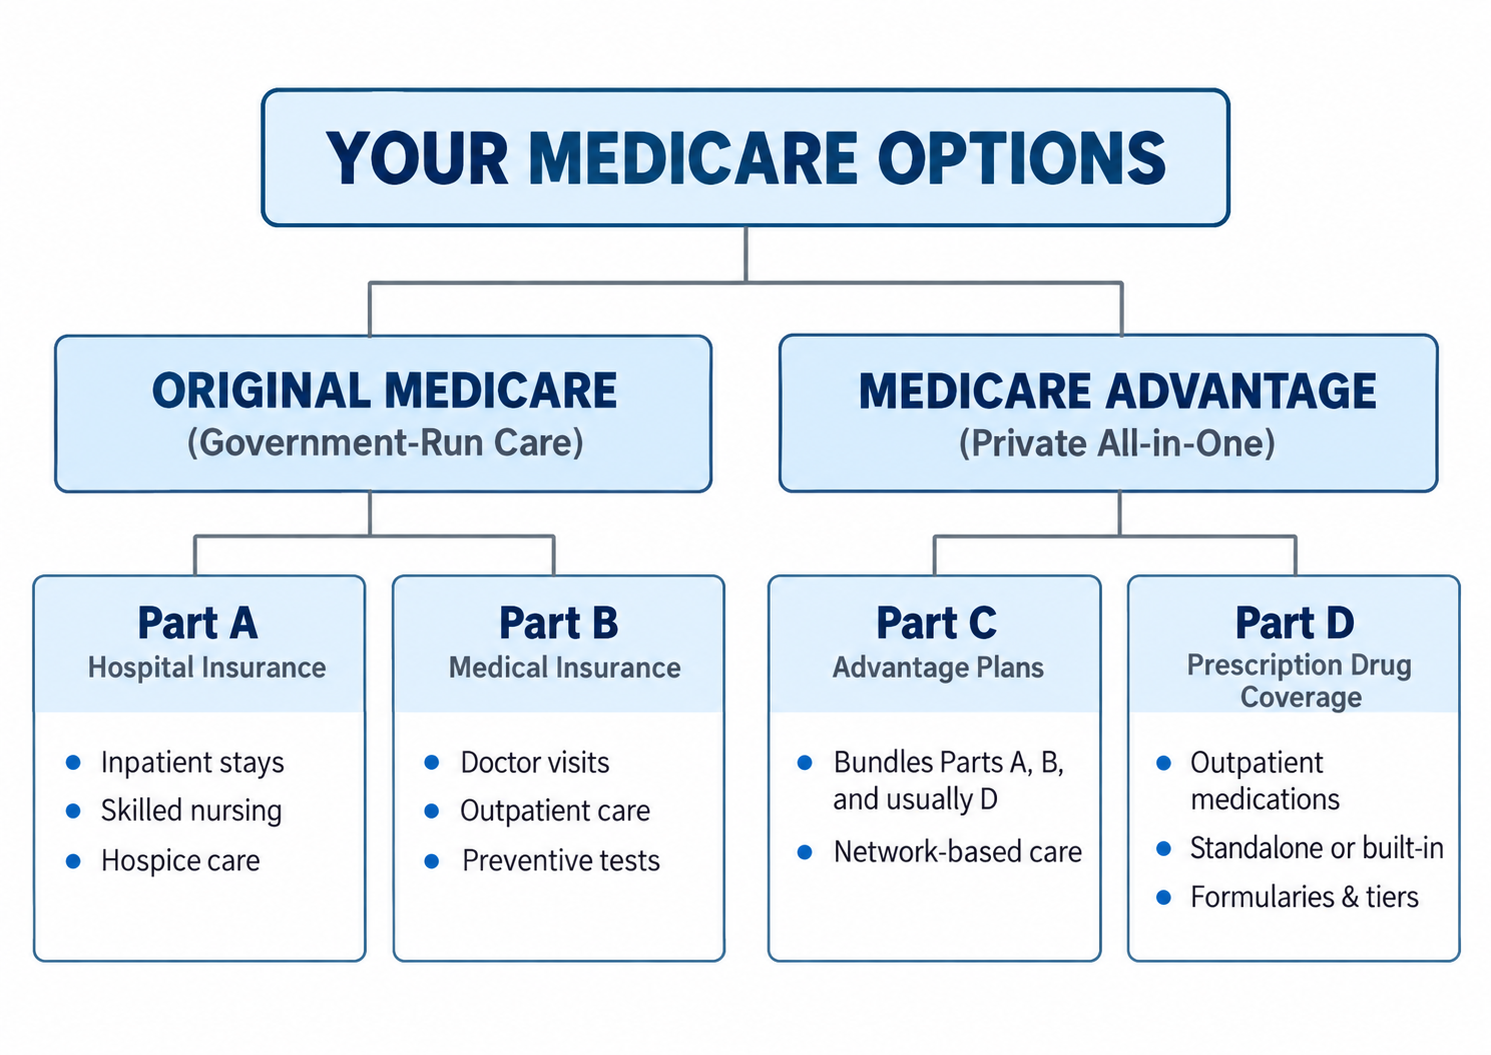
If you are new to Medicare, learning the terminology can feel like learning a new language. The program is divided into four distinct "parts"—Part A, Part B, Part C, and Part D—each covering a specific slice of your healthcare needs.
To build the right health plan for your retirement, you first need to understand what each part covers, how much it costs, and how they fit together. Here is your simple, straightforward guide to the ABC's (and D) of Medicare.
The Building Blocks: Parts A, B, C, and D
Medicare Part A: Hospital Insurance
Part A handles inpatient hospital care and major medical facility stays.
What It Covers: Inpatient hospital stays, skilled nursing facility care following a hospital stay, hospice care, and limited home healthcare services.
What It Costs: Most beneficiaries pay $0 per month for Part A (Premium-Free Part A) if they or their spouse paid Medicare taxes for at least 10 years (40 quarters).
Key Detail: Part A has an annual deductible per benefit period ($1,736 in 2026) before Medicare begins paying for inpatient care.
Medicare Part B: Outpatient & Medical Insurance
Part B covers routine medical care, doctor services, and outpatient care.
What It Covers: Doctor visits, specialist care, outpatient surgery, preventive screenings, lab tests, X-rays, vaccines, and durable medical equipment (like wheelchairs or walkers).
What It Costs: Part B requires a monthly premium paid to the federal government (the standard Part B premium is $202.90/month in 2026, though higher-income earners may pay more due to IRMAA).
Key Detail: After meeting your annual Part B deductible ($283 in 2026), Medicare generally pays 80% of covered services, leaving you responsible for the remaining 20% coinsurance—with no limit on out-of-pocket spending.
Together, Part A + Part B = "Original Medicare"
Original Medicare is administered directly by the federal government and allows you to visit any doctor or hospital nationwide that accepts Medicare
Medicare Part C: Medicare Advantage Plans
Part C, known as Medicare Advantage, is an all-in-one private alternative to Original Medicare.
What It Covers: By federal law, Medicare Advantage plans must cover everything included in Part A and Part B. Most plans also bundle prescription drug coverage (Part D) and extra perks like routine dental care, vision care, hearing aids, and fitness memberships.
How It Works: Instead of the federal government paying your doctors directly, Medicare pays a private health insurance company (like UnitedHealthcare, Humana, or Aetna) to manage your care.
Key Detail: Advantage plans typically restrict care to a local network of doctors (HMO or PPO) and often require prior authorizations for procedures. However, unlike Original Medicare, all Part C plans include a mandatory Maximum Out-of-Pocket (MOOP) cap to limit your financial exposure each year.
Medicare Part D: Prescription Drug Coverage
Part D provides standalone coverage for outpatient prescription medications.
What It Covers: Brand-name and generic prescription medications filled at retail or mail-order pharmacies.
How You Get It: You can buy a standalone Part D plan to add to Original Medicare (Parts A & B), or it may be built directly into a Medicare Advantage plan.
Key Detail: In 2026, out-of-pocket prescription costs are capped at $2,100 per year under federal Part D reforms. Once you reach this cap, you pay $0 for your covered drugs for the remainder of the calendar year.
Comparing Your Two Main Pathways
When setting up your Medicare benefits, you must choose between two primary paths:
Feature | Option 1: Original Medicare (A + B) + Medigap + Part D | Option 2: Medicare Advantage (Part C) |
|---|---|---|
Provider Choice | Nationwide — Any provider accepting Medicare | Local — Network-restricted (HMO / PPO) |
Referrals Required? | No — See specialists without referrals | Often yes (especially HMO plans) |
Monthly Cost | Higher fixed premiums (Part B + Medigap + Part D) | Lower premiums (Often $0 + Part B premium) |
Out-of-Pocket Risk | Extremely low / predictable per visit | Pay-as-you-go up to yearly MOOP cap ($9,250 max) |
Extra Benefits | None (Requires separate dental/vision policies) | Often includes dental, vision, hearing, & wellness |
3 Questions to Ask Before Choosing Your Path
Do you travel often or live in multiple states throughout the year?
If yes, Original Medicare + Medigap gives you complete freedom to visit any doctor in the country.
Do you take multiple daily brand-name or specialty medications?
Check the drug lists (formularies) of standalone Part D plans vs. Medicare Advantage plans to ensure your medications are covered at the lowest tier.
Do you prefer a low monthly premium or predictable out-of-pocket medical bills?
Medicare Advantage offers lower initial monthly payments, while Original Medicare combined with a Supplement plan eliminates unexpected medical bills when health emergencies happen.
Need Help Navigating Your Options?
Connect with an Independent Licensed Insurance Broker who can walk you through your options and help you make a confident decision.
📞Lauren Metzer Call: (412) 770-6477 TTY 711 M-F (9AM - 5PM) to connect with a Licensed Medicare Insurance Agent
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options. Not connected with or endorsed by the United States government or the federal Medicare program.

METZLER HEALTH SOLUTIONS
LEGAL

Disclaimer: Not affiliated with or endorsed by the government of Federal Medicare program. Medicare has neither reviewed nor endorsed this information. For accommodations of persons with special needs, please call 888-576-7550 TTY 711 (M-F 9am-5pm). By calling this number you will be directed to a licensed insurance agent. Not affiliated with or endorsed by the government of Federal Medicare program.
We do not offer every plan available in your area. Currently, we represent 8 organizations which offer 63 products in your area. Please contact Medicare.gov, 1‑800‑MEDICARE, or your local State Health Insurance Program to get information on all of your options.
© Copyright 2026. Metzler Health Solutions. All Rights Reserved.